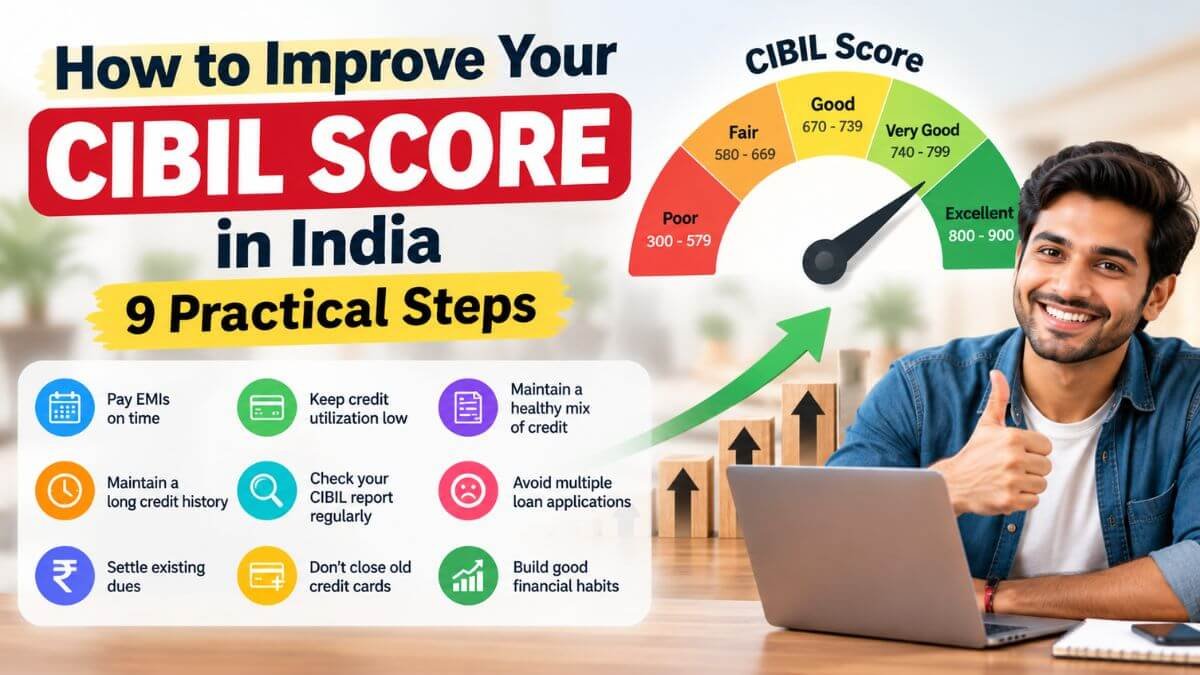
A low credit score can mean a rejected loan, a smaller amount, or a higher interest rate. The good news is that a credit score is not fixed. It reflects how you have handled credit, and it improves when your habits do. This guide explains what drives your CIBIL score and the steps that help most.
Quick answer
- CIBIL scores range from 300 to 900. Many lenders prefer a score of 750 or above.
- Paying every EMI and card bill on time matters most. Payment history is one of the biggest factors.
- Keep credit card usage low, avoid unnecessary new credit, and fix errors on your report.
- Improvement takes months of steady behaviour. Nobody can honestly guarantee a quick jump.
What affects your credit score?
| Factor | What it means | What to do |
|---|---|---|
| Payment history | Whether you pay EMIs and card bills on time | Pay on time, every time |
| Credit utilisation | How much of your card limit you use | Keep usage low, ideally below about 30% of the limit |
| Length of credit history | How long you have had credit | Keep your oldest accounts open and in good standing |
| Credit mix | The types of credit you hold | Do not take loans just to change your mix |
| New enquiries | How often you apply for credit | Apply only when you really need to |
CIBIL does not publish exact weights for each factor, but payment history is widely seen as the most important one.
Step 1: Check your credit report for errors
Under RBI rules, you can get one free full credit report from each credit bureau every calendar year. India has four bureaus: TransUnion CIBIL, Experian, Equifax and CRIF High Mark. Read the report carefully. Look for loans that are not yours, payments marked late that you paid on time, and wrong personal details. If you find an error, raise a dispute with both the lender and the bureau.
Step 2: Pay every EMI and card bill on time
This is the single most useful habit. Set up auto-debit for EMIs and at least the minimum amount on credit cards, and keep enough balance in the account a day or two before the due date. If you have already missed a payment, read how a missed EMI affects your credit score and pay the overdue amount as soon as you can.
Step 3: Clear overdue amounts and avoid “settled” accounts
If you cannot pay a loan in full, you may be offered a settlement. A loan marked “settled” (you paid less than you owed) looks worse to future lenders than one marked “closed” (paid in full). If you are in difficulty, speak to your lender about a revised repayment schedule before the account goes badly overdue.
Step 4: Keep your credit card usage low
Using most of your card limit makes you look dependent on credit. A common rule of thumb is to use less than about 30% of your limit. If your spending is high, ask for a limit increase (without spending more), or spread spending across cards and pay the bill in full each month.
Step 5: Do not close your oldest card without thinking
An old account with a clean record adds to the length of your credit history. If a card has no annual fee, keeping it open and using it for a small purchase now and then is usually better than closing it.
Step 6: Apply for new credit only when needed
Every time you apply for a loan or card, the lender checks your report and a hard enquiry is recorded. Several applications in a short time can make lenders think you are desperate for credit. Compare offers using eligibility checkers that use a soft check, and apply only to the lender you have chosen.
Step 7: Be careful with guarantees and joint loans
If you stand guarantor for someone’s loan, or take a joint loan, your credit report can be affected when the other person misses payments. Think carefully before you agree.
Step 8: Borrow only from regulated lenders
Loans from regulated banks and NBFCs are reported to credit bureaus, which helps you build a record when you repay on time. Illegal apps cause harm in other ways. Before you borrow, check whether a loan app is RBI-registered. If you are considering a short-term loan, compare a payday loan with a personal loan first.
Step 9: Be patient and track your progress
There is no fixed timeline. Late payments lose weight as time passes and as you add months of on-time payments. Check your report once or twice a year, and watch for any new errors.
Beware of “credit repair” promises
Some companies claim they can raise your score quickly or remove genuine negative entries for a fee. Genuine late payments cannot simply be deleted. Only incorrect entries can be corrected, and you can raise a dispute yourself without paying anyone. Never share OTPs, passwords or card details with anyone claiming to help with your score.
FAQs
What is a good CIBIL score?
Scores run from 300 to 900. Lenders set their own cut-offs, but many prefer 750 or above.
How long does it take to improve a credit score?
It depends on your starting point. Expect months of steady on-time payments and lower card usage, not days.
Does checking my own score reduce it?
No. Checking your own score is a soft enquiry. Applications for new loans or cards are hard enquiries, which can lower it slightly.
Will closing a loan improve my score?
Not always. Closing a loan that you paid on time is good for your record, but the score can move up or down a little afterwards because your credit mix and active accounts change.
Can I build a score from scratch?
Yes. Start with a small credit product you can repay easily, such as a credit card with a low limit or a small loan, and pay on time every month.
This article is for general information and is not financial advice. Scoring methods are set by credit bureaus and can change.